There is no single Public Liability Insurance limit that every tradie needs. Common limits include $5 million, $10 million and $20 million, but the amount that may be appropriate can depend on your trade, work locations, contracts, licence requirements, clients and the activities accepted by the insurer.
Before choosing a limit, check any contract, tender, site-access or licensing requirements that apply to your work. A higher limit also does not automatically mean broader cover because exclusions, activity restrictions and other policy terms still apply.
This information is general only and does not take into account your objectives, financial situation or needs. Cover is subject to policy terms, conditions, limits, exclusions and insurer acceptance.
Quick summary
- There is no single Public Liability Insurance limit that applies to every tradie or contractor.
- $5 Million, $10 million and $20 million are common limits available in the Australian market, although available limits depend on the insurer and policy.
- Contracts, tenders, principal contractors, site operators and some licensing requirements may specify a minimum Public Liability Insurance limit.
- The type of trade work, project locations, subcontractor use and third-party exposure can affect the limit and policy structure that should be considered.
- A $20 million policy is not automatically broader than a $10 million policy because the policy wording, insured activities, exclusions and endorsements also matter.
- Your Public Liability Insurance should be reviewed when you take on different contracts, activities, locations or project requirements.
How Much Public Liability Insurance Do I Need?
The amount of Public Liability Insurance you may need should be considered against the work your business actually performs and any minimum requirements imposed on that work.
For some tradies, the first figure to check is already written into a building contract, subcontract agreement, tender document, licence condition or site-access requirement. Another business may have more flexibility and need to consider the type of third-party property, people and sites around its work.
Public Liability Insurance may respond to certain claims alleging third-party injury or property damage arising from declared business activities. The limit of liability is one part of that cover. It represents the maximum amount available under the relevant section of the policy, subject to how the policy applies, its terms, conditions, exclusions and any applicable sub-limits.
Choosing the limit should therefore involve more than selecting the highest number available.
What Is the Difference Between $5 Million, $10 Million and $20 Million Public Liability Insurance?
$5 million, $10 million and $20 million are common Public Liability Insurance limits, but none should be treated as the automatic choice for a particular trade.
The required amount can change from one contract or site to another, even when the contractor performs the same type of work.
These are general examples only. A particular limit should not be assumed to suit a business or satisfy a contract, licence or site requirement. Available limits and cover are subject to insurer acceptance and the applicable policy terms, conditions and exclusions.
What Determines How Much Public Liability Insurance a Tradie May Need?
The limit should reflect more than the name of your trade. Insurers and businesses may need to consider what work is actually being performed, where it is performed and the contractual arrangements around the job.
Factors to consider when reviewing your limit
Your trade activities
The work disclosed to the insurer should accurately reflect the services your business actually performs.
Contract requirements
A client, builder or principal may specify a particular limit and additional insurance wording.
Where you work
Residential, commercial, civil, industrial and mining sites can involve different insurance requirements.
Third-Party exposure
Consider the people, property, structures and services around the work being performed.
Employees and subcontractors
Workforce and subcontractor arrangements should be disclosed accurately and may affect the policy structure.
Licence and site conditions
Some occupations, licences or sites may have specific Public Liability Insurance requirements that should be checked separately.
Your Trade Activities
A carpenter completing residential fit-outs does not necessarily have the same exposure or contractual requirements as a structural steel contractor working on major commercial projects.
Occupation descriptions also matter. The policy should reflect all declared work accepted by the insurer rather than relying on a broad label that does not accurately describe the business.
The Properties and Sites Where You Work
A tradie working primarily in private homes may encounter different third-party property and site requirements from a contractor working at shopping centres, schools, government facilities, mine sites or large construction projects.
Work across multiple types of sites should be disclosed when arranging or reviewing cover.
The Contracts You Accept
A contract can specify the Public Liability Insurance limit that a contractor is expected to maintain. It may also request other insurance provisions such as Principal’s Indemnity, Cross Liability, Waiver of Subrogation or project-specific Certificates of Currency, depending on the contract and insurer acceptance.
The dollar limit is therefore only one part of a contract insurance schedule.
Your Employees and Subcontractors
The number of workers and the way subcontractors are used can affect the information an insurer needs when assessing Public Liability Insurance.
Subcontractors may also be required to maintain their own insurance under a contract or site arrangement. A business should not assume that its own Public Liability Insurance automatically satisfies the insurance obligations of every subcontractor working with it.
Does a Higher Public Liability Insurance Limit Mean Better Cover?
Not necessarily. A higher limit increases the amount potentially available under the relevant policy section, but it does not automatically change which activities, events or property are insured.
The key distinction
Your liability limit Is the amount available under the applicable section of the policy. Your policy scope determines what activities, claims and circumstances may be covered. Increasing the limit does not automatically remove exclusions, activity restrictions, excesses, sub-limits or insurer conditions.
For example, a $20 million policy that excludes a particular activity should not be assumed to cover that activity simply because its liability limit is higher than another policy.
The occupation description, exclusions, endorsements and contract requirements should be reviewed alongside the liability limit.
Can a Contract Tell Me How Much Public Liability Insurance I Need?
Yes. Contracts commonly set insurance obligations for contractors, and Public Liability Insurance may be one of the required policies.
The Contract May State:
- The minimum Public Liability Insurance limit
- The period for which the insurance must be maintained
- Which business activities or projects must be insured
- Whether the principal needs to be noted or indemnified, where available
- Whether Cross Liability or Waiver of Subrogation wording is requested
- The form of Certificate of Currency or other evidence required
Check the insurance schedule before work starts
If a new contract specifies a Public Liability Insurance limit or special wording, compare those requirements with the policy you currently hold and raise any differences before relying on the policy for that job.
Whether requested wording can be provided depends on the policy, declared activities and insurer approval. A policy or Certificate of Currency should not be assumed to satisfy every contract, tender, licence or site-access requirement.
Australian Government guidance for contractors also states that contracts should identify each party’s insurance obligations. This makes the contract itself an important document when determining the amount and type of insurance being requested.
Is There a Minimum Public Liability Insurance Requirement in Australia?
There is no single Public Liability Insurance limit that applies to every business or tradie across Australia.
Requirements can differ according to occupation, state or territory, licence conditions, contract terms and the site where work is performed. Australian Government guidance notes that some states and territories require Public Liability Insurance for certain occupations.
A contractor should therefore check the rules applying to the specific trade and jurisdiction rather than assuming that $5 million, $10 million or $20 million is a universal legal minimum.
Where a licence or statutory requirement applies, confirm the current requirement with the relevant state or territory regulator or licensing authority.
How Can Public Liability Insurance Limits Differ Between Jobs?
A tradie can perform the same general trade but face different insurance requirements from one job to the next.
These examples are general only and do not mean that a particular limit or policy will be suitable or accepted for the work described. Requirements and cover depend on the actual contract, business activities, jurisdiction and policy wording.
What Does Public Liability Insurance Generally Cover?
Public Liability Insurance may respond to certain third-party personal injury or property damage claims connected with your declared business activities.
Depending on the Policy and Circumstances, This May Include:
- Claims alleging accidental damage to a client’s property
- Claims involving damage to nearby third-party property or services
- Claims involving injury to a client, site visitor or member of the public
- Products Liability for products supplied, sold or installed, where included
- Legal defence costs associated with an insured liability claim, subject to the policy wording
Some activities or property may be restricted or excluded. Property in your care, custody or control, work at certain heights or depths, hazardous work and other trade-specific exposures can require particular attention.
You can read more about the scope of Public Liability Insurance.
What Does the Liability Limit Not Tell You?
The liability limit does not tell you everything about a Public Liability Insurance policy.
Two Policies with the Same $10 Million or $20 Million Limit Can Have Different:
- Occupation descriptions
- Accepted business activities
- Exclusions
- Height or depth restrictions
- Subcontractor conditions
- Excesses
- Endorsements
- Territorial limits
- Contractual Liability provisions
The policy wording should therefore be considered alongside the dollar limit.
Should I Increase My Public Liability Insurance When My Business Grows?
Growth does not automatically mean a higher Public Liability Insurance limit is required, but changes to the business can be a reason to review the policy.
A Review May Be Appropriate When You:
- Take on larger contracts or different types of projects
- Begin commercial, civil, industrial or mining work
- Add employees or regularly engage subcontractors
- Expand into new services or activities
- Work at new types of sites
- Start working for principals with different insurance requirements
- Move into another state or territory
- Receive a tender or contract requiring a different liability limit
The purpose of the review is to compare the changed business activities and contractual requirements against the existing policy, not simply to increase the limit automatically.
How Much Does Public Liability Insurance Cost at Different Limits?
The Public Liability Insurance limit can affect the premium, but it is only one pricing factor.
Insurers may also consider the occupation, turnover, number of workers, subcontractor costs, work locations, activities, claims history and other underwriting information. A $20 million limit should therefore not be assumed to cost a fixed amount more than a $10 million limit.
For a separate breakdown of premium factors, see our guide to how much Public Liability Insurance costs.
How Do I Work Out How Much Public Liability Insurance I Need?
A practical starting point is to check the requirements you already have and then compare them with your actual business activities.
- Check your contracts. Look for a stated Public Liability Insurance limit and any requested endorsements or insured-party wording.
- Check site and licensing requirements. Confirm whether your trade, licence or work location has its own insurance conditions.
- Review your declared activities. Make sure the insurer has an accurate description of the work your business performs.
- Consider where you work. Residential, commercial, civil, industrial and mining projects can involve different requirements.
- Check the policy wording. Review exclusions, conditions, limits and endorsements rather than relying on the liability figure alone.
- Review new jobs before relying on the existing policy. A new principal or contract may request a different limit or policy wording.
How We May Be Able to Help
All Trades Cover is a specialist insurance brokerage for trades, construction, mining and heavy industry businesses.
Depending on Your Business, Insurer and Project Requirements, We May Be Able to Help With:
- Reviewing the Public Liability Insurance limit requested under a contract or tender
- Comparing available Public Liability Insurance options
- Checking whether declared activities and work locations are reflected in the policy information
- Approaching insurers about Principal’s Indemnity, Waiver of Subrogation or other requested wording where available
- Arranging Certificates of Currency once cover and required wording have been confirmed
- Reviewing cover when your projects, activities or business operations change
- Supporting clients through the claims process
Insurer approval is required for policy changes, endorsements and amended documentation. Public Liability Insurance should not be assumed to satisfy every contract, licence, tender or site-access requirement.
Get a Public Liability Insurance quote or speak with All Trades Cover about your business and the insurance requirements applying to your work.
Frequently Asked Questions
Is $5 Million Public Liability Insurance Enough for a Tradie?
$5 million may be an available limit for some eligible businesses, but it should not be assumed to be enough for every tradie. Check your contracts, licences, client requirements, work activities and sites before choosing or relying on that limit.
Do I Need $10 Million Public Liability Insurance?
$10 million is a commonly available limit and may be requested under some commercial contracts or site arrangements. Whether you need that amount depends on the requirements applying to your work and the policy offered by the insurer.
When Might a Tradie Need $20 Million Public Liability Insurance?
$20 million may be requested under some larger commercial, civil, infrastructure, mining or principal-contractor arrangements. The contract or site insurance schedule should be checked rather than assuming $20 million is required for every larger job.
Is $10 Million Public Liability Insurance Standard in Australia?
There is no single Public Liability Insurance limit that should be treated as the Australian standard for every business. $10 million is a common market limit, but actual requirements vary between businesses, contracts, occupations and jurisdictions.
Is Public Liability Insurance Compulsory for Tradies?
Public Liability Insurance is not subject to one universal requirement for every tradie in Australia. Some occupations or licences may have state or territory requirements, while builders, principal contractors, clients or site operators may also make Public Liability Insurance a contractual condition.
Can a Builder Require Me to Hold $20 Million Public Liability Insurance?
A builder or principal contractor may specify an insurance limit in a subcontract or project insurance schedule. Contractors should check the requirement against their current policy and confirm with their insurer or broker whether the requested limit and wording are available.
Does $20 Million Public Liability Insurance Cover More Types of Claims Than $10 Million?
Not automatically. The higher figure relates to the policy limit, while the types of claims that may be covered depend on the policy wording, declared activities, exclusions, endorsements and circumstances of the claim.
Do Subcontractors Need Their Own Public Liability Insurance?
Subcontractors are often required to maintain their own Public Liability Insurance under contracts or site requirements, but the required amount can vary. The subcontract agreement and applicable site requirements should be checked.
Does a Certificate of Currency Show That I Have Enough Public Liability Insurance?
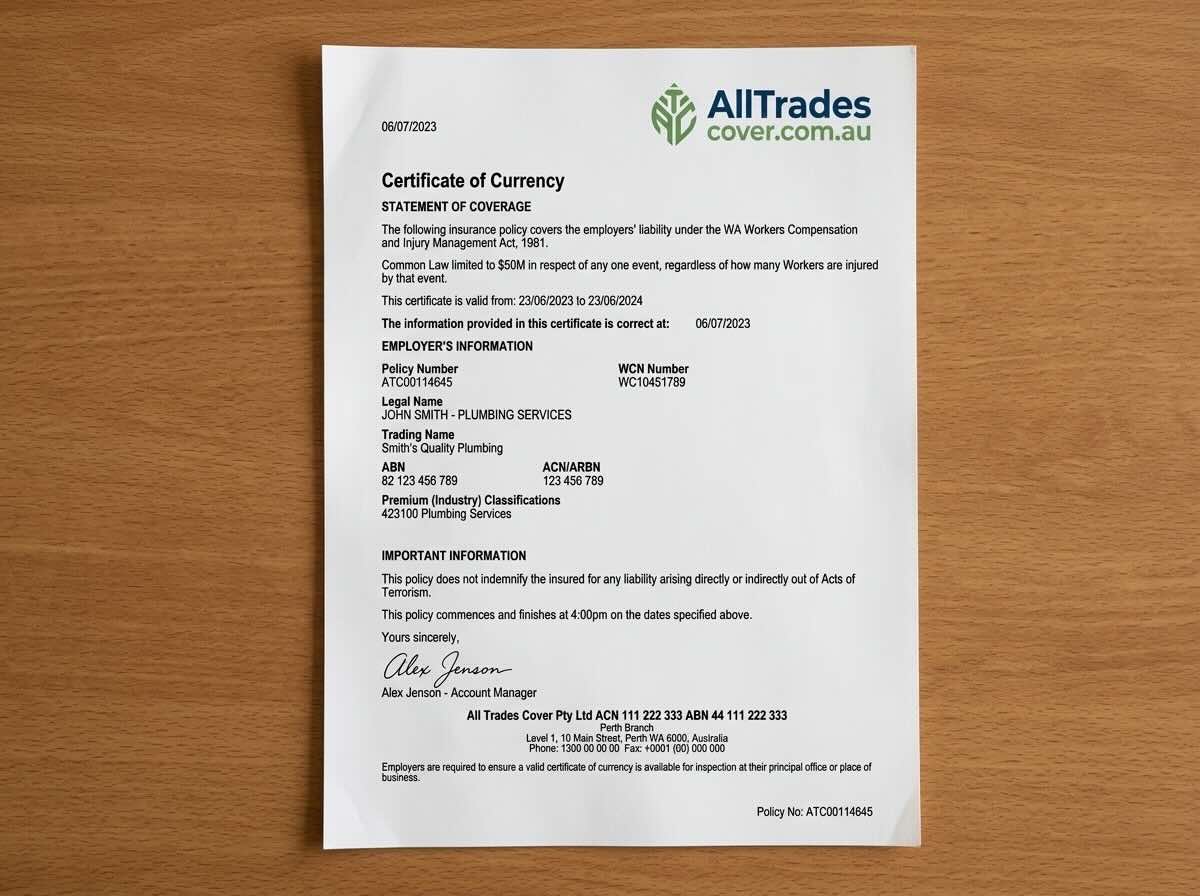
A Certificate of Currency can provide evidence of the insurance arranged at the time it is issued, including information such as the policy period and limit. It should not be assumed to prove that every activity, endorsement or contractual requirement is satisfied.
Should I Increase My Cover Before Starting a Bigger Project?
A larger project can be a reason to review your Public Liability Insurance, but a higher limit is not automatically required. Check the new contract value, insurance schedule, work activities, site requirements and existing policy before making changes.
This information is general only and does not take into account your objectives, financial situation or needs. Cover is subject to policy terms, conditions, limits, exclusions and insurer acceptance.